Blog · Prediction markets
Bankroll Management and the Kelly Criterion for Prediction Markets
Prediction market talk is full of picks and almost empty of sizes. Yet the question "how much do I put in?" decides your survival at least as much as "what do I buy?". You can estimate probabilities better than the market and still go broke, purely by betting too much on each trade.
That is what bankroll management is about, and the classic tool for answering it with numbers is the Kelly criterion. This article explains it in plain English, walks through a complete example, and covers the version sensible people actually use: fractional Kelly.
What bankroll management is (and why it beats being right)
Your bankroll is the money you dedicate to this: a separate, pre-defined amount you could lose entirely without it changing your life. Bankroll management is the set of rules deciding what fraction of that amount you risk on each market.
Why is it so critical? Variance. A bet with a true 70% chance of winning fails three times out of ten, and losing streaks arrive sooner or later. Risk too much per trade and a perfectly normal streak knocks you out of the game even when your judgment was good. Ruin is rarely a punishment for bad analysis, it is almost always a punishment for bad sizing.
The Kelly criterion in plain English
The Kelly criterion is a formula published in 1956 by John Kelly, a Bell Labs researcher, and it answers exactly one question: what fraction of my bankroll should I risk to maximize its long-run growth?
In a binary prediction market the formula comes out especially clean. If the share price is `c` (remember: the price, between $0 and $1, is the implied probability, and every winning share pays exactly $1) and your estimated probability is `p`:
*f\ = (p − c) / (1 − c)**
Translation: the numerator is your edge (how far you think the market undershoots) and the denominator is what you win per dollar of price when you're right. The output, f\*, is the fraction of your bankroll Kelly suggests risking.
Two properties worth engraving somewhere:
- If your estimate is at or below the price (p ≤ c), the formula returns zero or negative: don't bet. This is by far the most valuable advice Kelly gives, and the most widely ignored.
- The bigger your edge, the more it tells you to risk, but the growth it promises only materializes if your `p` is right. That is the trap, and we get to it below.
A worked example
Say your bankroll is $1,000. You find a market where YES trades at $0.60 and, after your own analysis, you estimate the true probability at 70%.
- Edge: 0.70 − 0.60 = 0.10
- Denominator: 1 − 0.60 = 0.40
- Full Kelly: 0.10 / 0.40 = 0.25 → 25% of your bankroll: $250
$250 at $0.60 buys about 416 shares. If you're right, each share pays $1: you receive $416, roughly $166 in profit. If you're wrong, the $250 is gone.
And here an alarm should go off: a quarter of your entire bankroll on a single bet that fails 30% of the time? That is exactly what full Kelly prescribes. The formula is optimal only if your 70% is exact, and it never is.
Recorded straight off the map, no sound.
Fractional Kelly: the version sensible people use
Full Kelly's problem is that it punishes estimation errors asymmetrically. Betting below the optimum costs you a little growth; betting above it destroys growth and spikes your risk of ruin. Since your `p` always carries error (and beginners almost always overrate themselves) trading at full Kelly means, in practice, systematically overbetting.
The fix is fractional Kelly: compute f\* and risk only a fraction of it.
- Half Kelly in our example: $125. You keep most of the theoretical growth with half the swings.
- Quarter Kelly: about $62. Slower growth, but a bankroll curve you can live with.
The rule of thumb repeated by people who survive years in this game: half Kelly at most, quarter Kelly while you're learning, plus an absolute per-market cap (say, never more than 5% of the bankroll) in case the formula and your optimism gang up on you.
The hard part: estimating "p"
Kelly does not create edge; it only manages it. Feed it a made-up probability and it will return a beautifully sized bad bet. The real work is estimating `p` independently of the price, we cover the groundwork in how to calculate implied probability and expected value in betting.
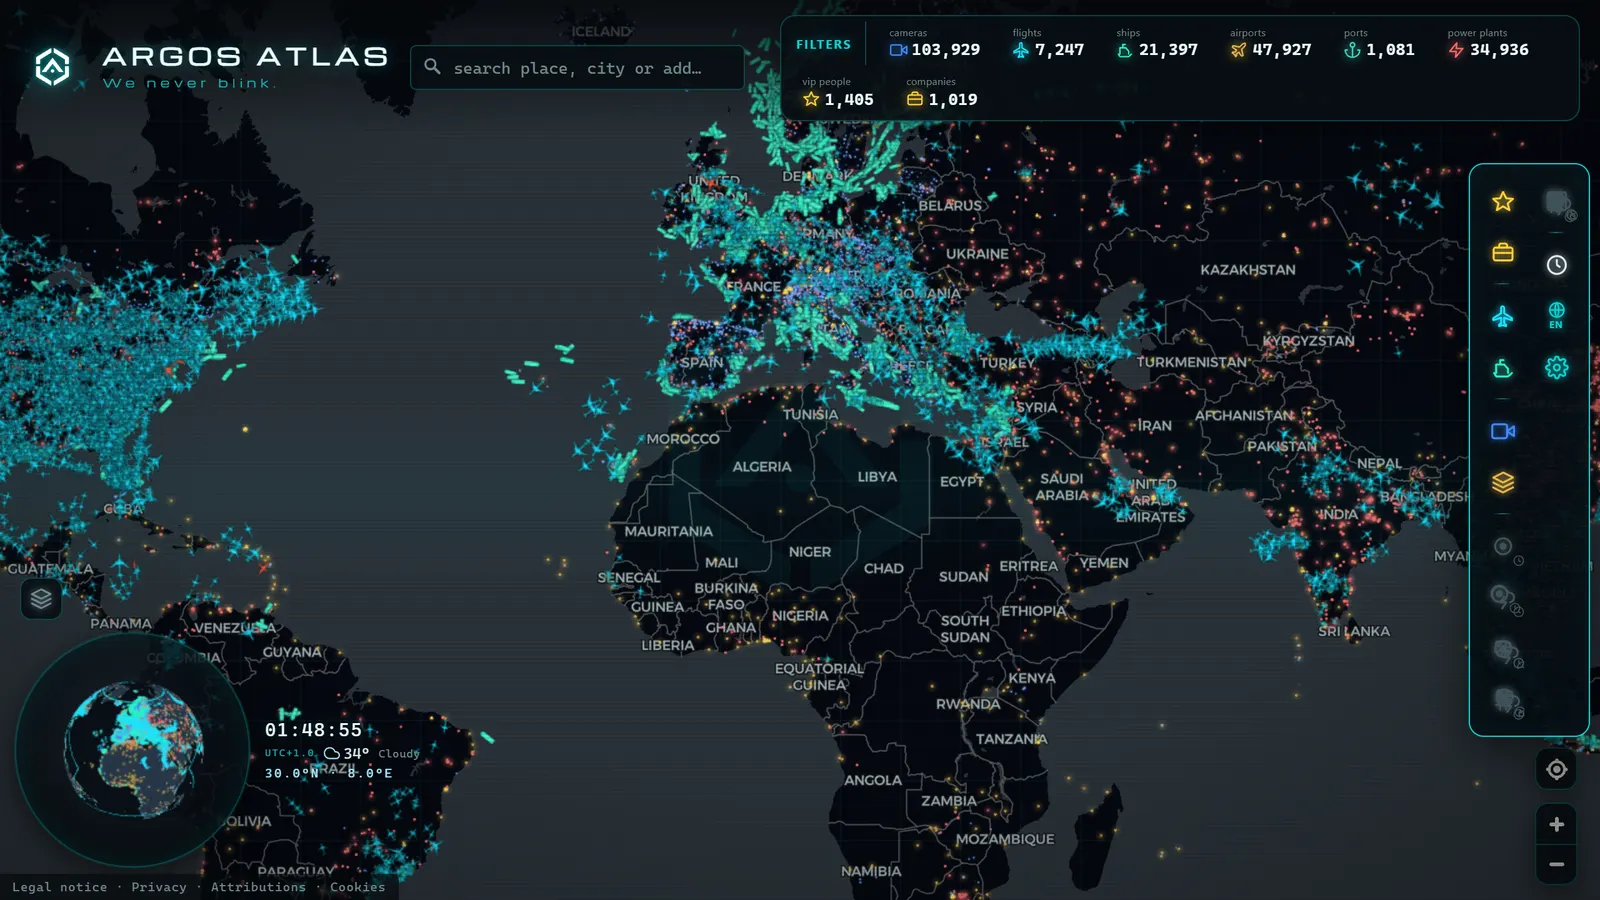
One practical aid for that contrast: Argos Atlas's geolocated predictions plot Polymarket markets on the map at the exact location of the underlying event, with a proprietary signal ("ARGOS") that compares the market's odds against an independent estimate. It is not a buy recommendation, it's a starting point for deciding where deeper research is worth your time.
Practical bankroll rules
- Keep it physically separate. If you decide to open a Polymarket account, deposit only the bankroll you defined and nothing more.
- Compute Kelly, bet a fraction (½ or ¼), and respect a fixed per-market cap.
- Watch correlated markets: three bets on the same underlying event are, risk-wise, one big bet.
- Keep a log of every trade with your estimated `p`, so you can audit your judgment with data.
- Stay honest about the context: recent on-chain analysis suggests only around 7-8% of wallets are profitable, as we detail in how many people actually make money on Polymarket. Bankroll management won't guarantee you join that group, but betting without it practically guarantees you won't.
This content is informational and does not constitute financial advice or an investment recommendation.
Frequently asked questions
What happens if I use full Kelly instead of fractional Kelly?
On paper you maximize long-run growth, but at the cost of brutal swings in your bankroll. And since your estimated probability is never exact, full Kelly in practice usually means overbetting, the single most destructive sizing error. That is why almost every serious operator uses half Kelly or a quarter.
Is Kelly useful if I don't know my exact probability?
Nobody knows it; you always work with estimates. Kelly still helps as a ceiling: it tells you the reasonable maximum, and fractional Kelly absorbs part of your estimation error. If you cannot estimate the probability even roughly, the problem is not the formula, it's that you shouldn't be in that market.
How big does my bankroll need to be?
Size doesn't change the math: percentages work the same with $100 or $10,000. What matters is that it is money kept separate from your living expenses, which you could lose entirely without drama. Starting small is the cheapest way to train the process.
Does Kelly work in markets with multiple outcomes?
The classic formula is for binary bets, which is what most Polymarket markets are (YES/NO). A generalization exists for multi-outcome markets, but it gets complicated fast. A practical approximation is to treat each outcome as binary and keep strict per-market caps.
- Limit Orders on Polymarket: The Quiet Way to Pay Less
- How Many People Actually Make Money on Polymarket? The Real Data
- Selling Before Resolution: Taking Profits in Prediction Markets
- Weather Prediction Markets: Trading the Degrees
- Crypto Prediction Markets: Price Exposure Without Buying the Asset
- Polymarket vs Kalshi: The Complete Comparison