Blog · Wealth, jets & yachts
How Billionaire Net Worth Is Calculated, Forbes, Bloomberg, and the Method Behind the Numbers
When you read that someone is «worth» a certain number of billions, the figure sounds like it came from a bank statement. It did not. The billionaire net worth figures published by Forbes, Bloomberg, and other rankings are estimates built from a methodology: share prices, valuations, comparable transactions, and a fair number of assumptions. Understanding how that number is constructed changes entirely the way you read the rich lists, why someone moves up three places in a week, why two rankings disagree, and why an enormous fortune can coexist with surprisingly little liquid cash. Here is how it works.
The essentials, in 20 seconds
- Net worth: assets minus liabilities, but in the biggest fortunes most of it is the value of corporate stakes, not cash in a bank.
- Publicly traded shares: valued from public regulatory filings and real-time share price, the most transparent and verifiable part of the calculation.
- Private companies, real estate and art: valued by comparables and conservative discounts, so the figure is a reasoned estimate, not a fact.
- Forbes: publishes an annual list plus a real-time tracker that updates fortunes as markets move.
- Bloomberg: runs its own Billionaires Index, updated daily with a separately published methodology.
What net worth actually means
Net worth is a straightforward subtraction: everything a person owns (assets) minus everything they owe (liabilities). So far, no different from anyone else's household budget. The difference lies in composition: in the world's largest fortunes, the bulk of net worth is not money in the bank, it is the value of corporate stakes.
Consider the founder of a major technology company who retains a significant portion of its shares. Their fortune is, essentially, the price of those shares multiplied by the number they hold. That is not cash: it is paper value that only converts to money when sold, and selling in large quantities carries tax, regulatory, and market implications.
Those stakes are supplemented by other assets: real estate, art, collections, aircraft, superyachts, and diversified financial investments. Liabilities are subtracted where known. That last qualifier («where known») is one of the system's greatest blind spots, as we will see.
The ranking methodology: the straightforward part and the difficult part
The teams that compile these rankings (as Forbes and Bloomberg document in their publicly available methodologies) combine hard data with estimates. The two halves are worth separating.
The straightforward part: publicly traded companies
When a fortune rests on shares in a listed company, valuation is nearly automatic. Major shareholders' stakes appear in public regulatory filings, and the share price is available in real time. Shares held multiplied by market price: that portion of the calculation is transparent and verifiable by anyone.
This is why the most «measurable» fortunes are those of founders of large publicly listed companies: the bulk of their net worth is visible to the market every second the exchange is open.
The difficult part: everything else
The remainder requires judgment:
- Privately held companies. There is no market price, so they are valued by comparables: a similar company that trades publicly or has recently been acquired is identified, and its multiples (applied to revenues or earnings) are adjusted with liquidity discounts. This is a reasoned estimate, not a fact.
- Real estate, art, and collections. These are appraised using reference market prices and, again, conservative discounts, because selling a mansion or a collection takes time and rarely achieves catalogue price.
- Debt and pledged shares. This is the major blind spot. Many billionaires take out enormous loans using their own shares as collateral (margin lending). Those private liabilities are not always public, and an imposing gross estate can conceal a considerably smaller net figure. Rankings subtract what they can document; what is invisible, is not subtracted.
Research teams supplement all of this with interviews, court and corporate documents, financial press coverage, and occasionally with the cooperation (or protest) of the subjects themselves, who sometimes consider a published figure too high and, curiously, sometimes too low.
Recorded straight off the map, no sound.
Why the numbers fluctuate daily
If the bulk of a fortune is in publicly traded shares, the implication is unavoidable: the stock market moves the rankings with every session. A sharp fall in a billionaire's main company drags their estimated net worth down that same day; a strong earnings report can send it soaring. That is why the top positions on these lists shift constantly, and why headlines of the form «X loses billions in a single day» do not mean someone burned money, they mean the shares are worth less today than yesterday.
This daily volatility is also the reason real-time rankings exist. An annual snapshot becomes stale within hours when the underlying asset is this sensitive to market conditions.
A billionaire does not «lose» billions in a day the way someone misplaces their wallet: what changes is the price the market places on what they own.
Forbes and Bloomberg (and how they differ)
Forbes has published its annual billionaires list for decades (the classic reference for wealth rankings) and also maintains a real-time tracker that updates fortunes linked to traded securities as markets move. The combination of the annual edition, more measured and deeply researched, with the daily scoreboard that captures the market's pulse is verifiable on the publication's own platform.
Bloomberg offers the most-cited alternative with its own Billionaires Index, updated daily with a published methodology. Both lists generally agree on who occupies the top positions, but disagree on exact figures because each team applies its own valuation criteria to the hard-to-price assets. That discrepancy is not an error: it is evidence that we are talking about estimates with different assumptions, not measurements.
Honest criticisms of the rankings
Taking these lists seriously requires knowing their limits. The most commonly cited:
- Opacity. Anyone who wants to conceal wealth has tools available: interposed companies, opaque jurisdictions, assets held in other people's names. The rankings capture what is visible and documentable.
- Over-estimation in private assets. Valuing a private company using comparables can diverge widely from what a buyer would actually pay.
- Net worth is not liquidity. Being worth a great deal on paper is different from being able to access that money. This confusion generates persistent misunderstandings in public debate.
- Family fortunes divided across vehicles. When wealth is split among many heirs or family trusts, deciding who gets credited with what is, again, a methodological convention.
None of these criticisms invalidates the rankings; the serious publications acknowledge them openly. What they invalidate is the naive reading of the figure as if it were an audited bank balance.
The trend matters more than the exact figure
Everything above implies a sensible way to read a wealth ranking: focus less on the number and more on the movement. Whether a particular fortune amounts to X billion or Y billion is debatable; that it has grown steadily over years, that it is increasingly concentrated in a single sector, or that the planet's top positions all depend on a handful of technology companies, those are robust signals even if each individual figure carries a margin of error.
The trend also tells stories: meteoric ascents tied to a stock market debut, crashes that track sector crises, generational transfers within family dynasties. Read carefully, a ranking is less a record table and more a seismograph of the economy.
From ranking to map
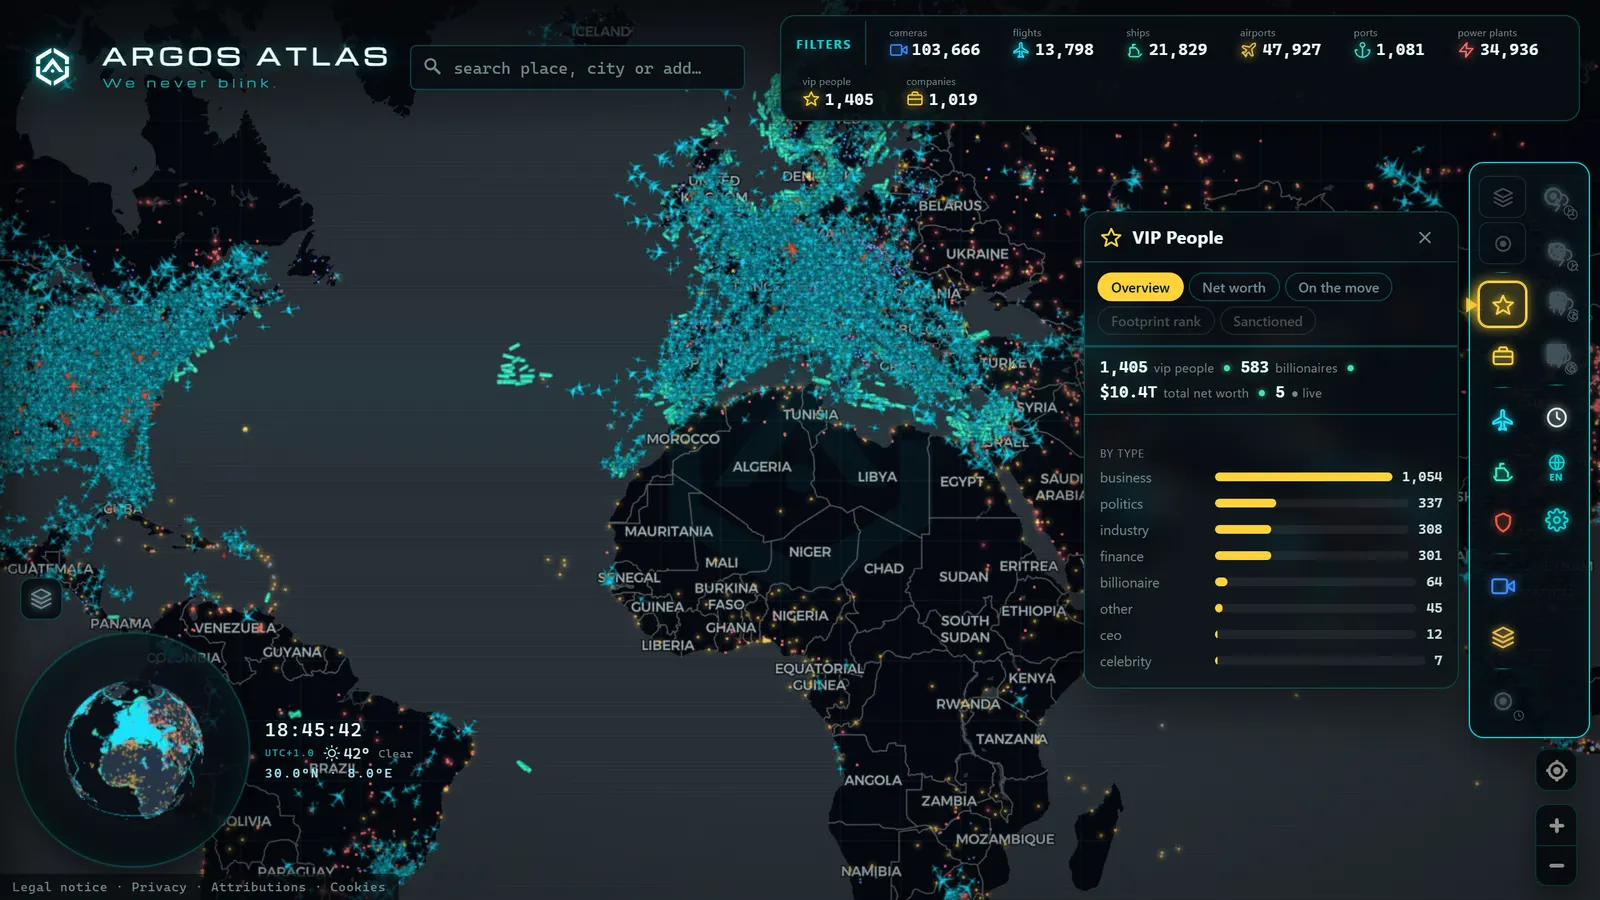
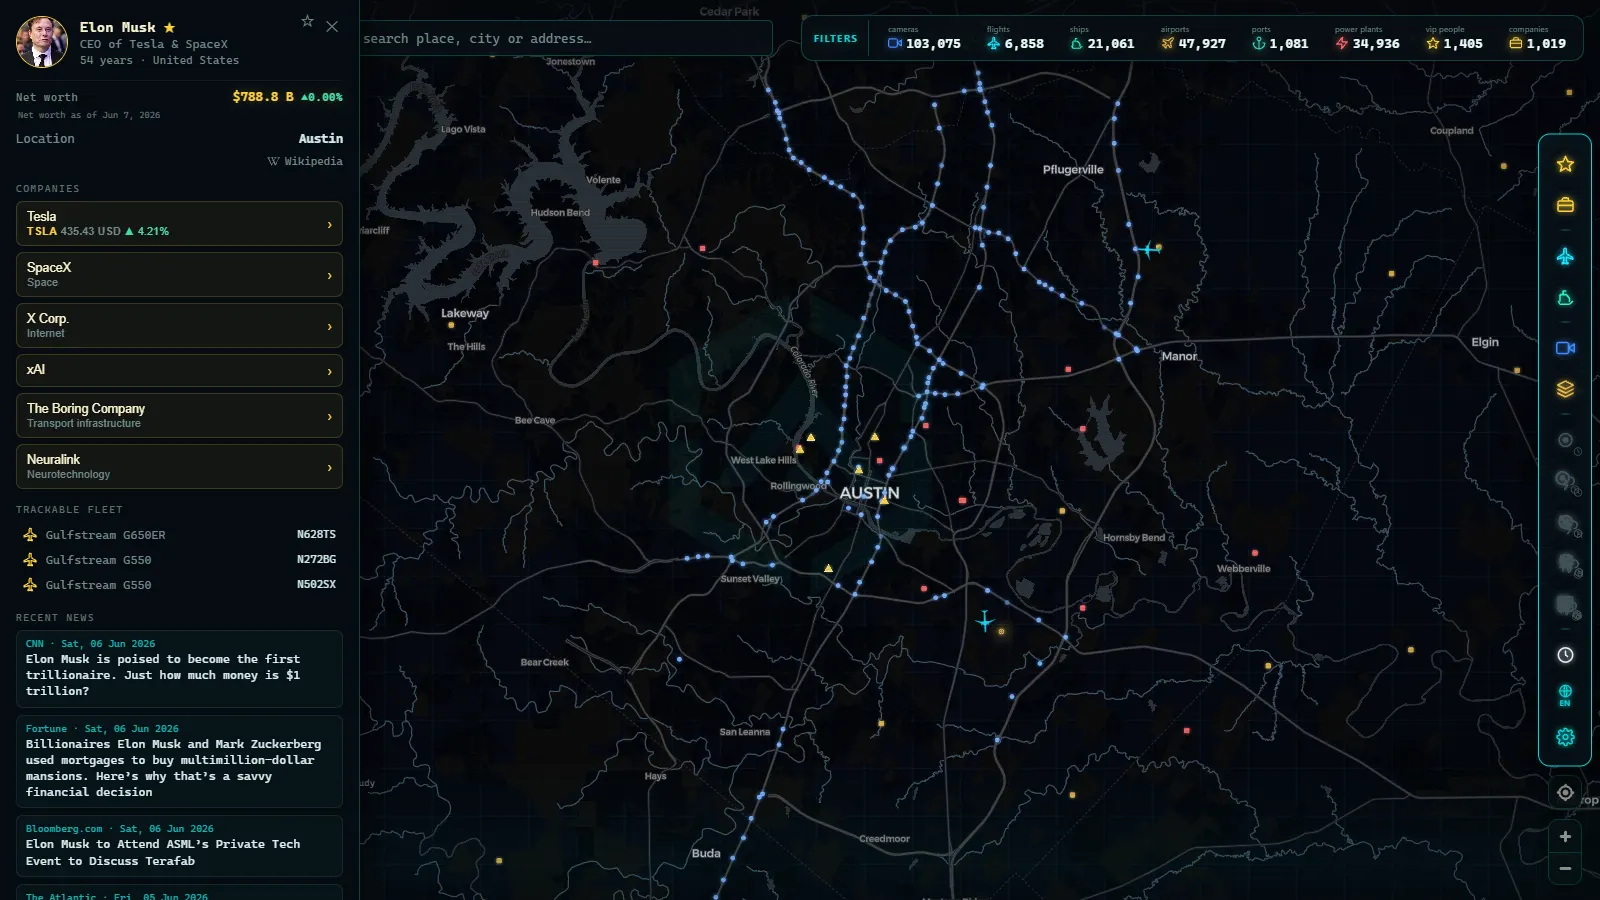
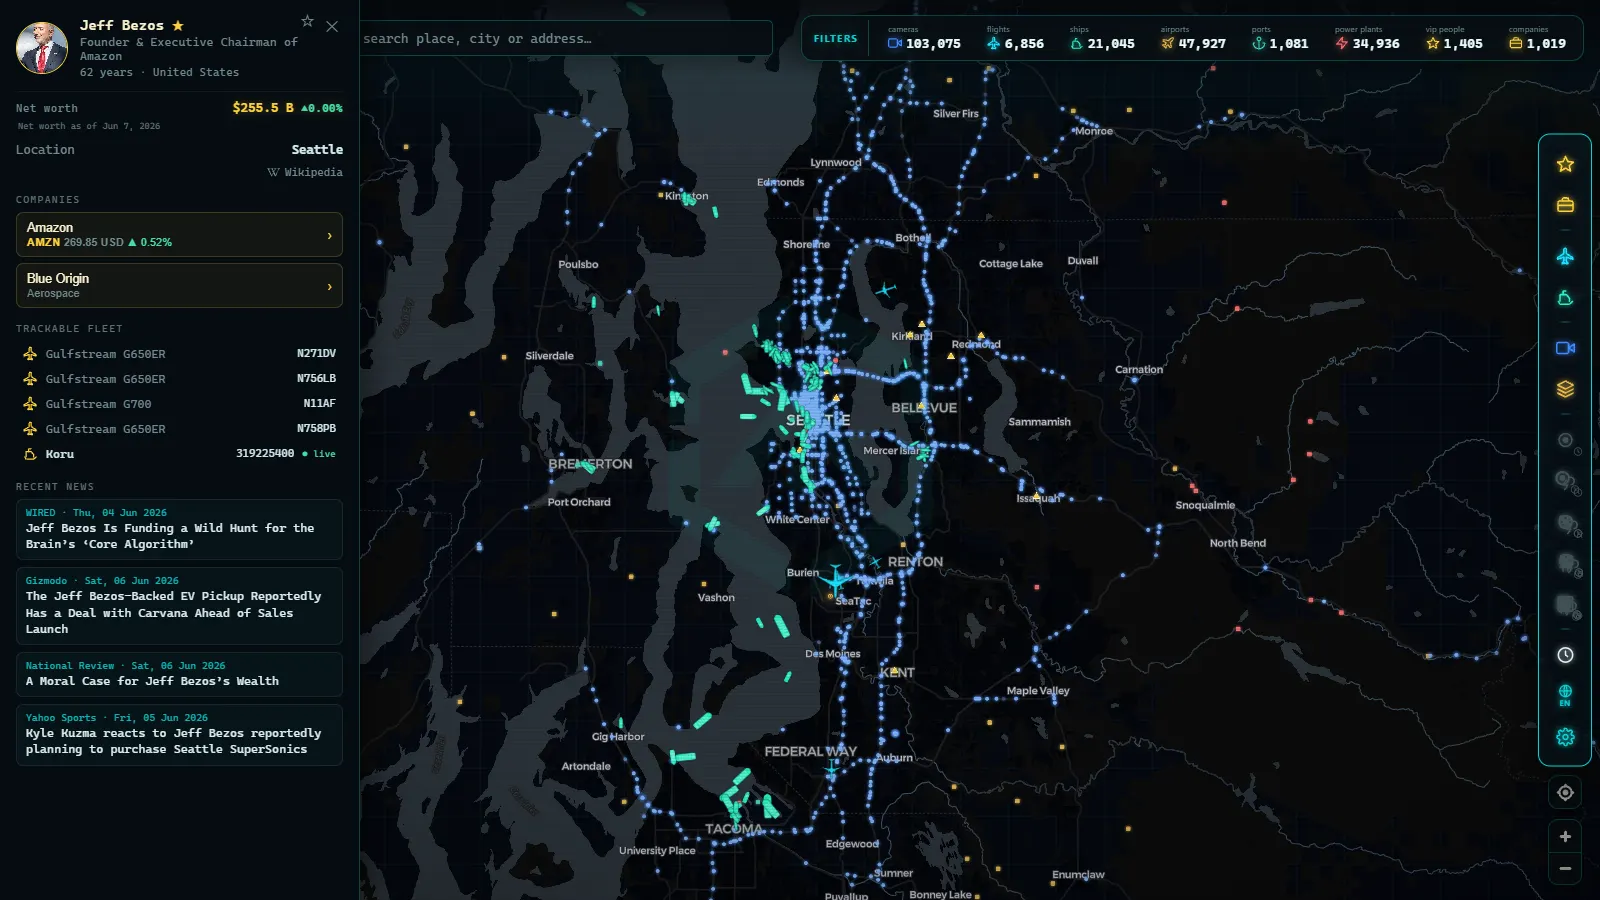
A list is useful; a list with geography is more so. Argos Atlas offers a net worth ranking with Forbes data updated daily, integrated into the world map: each person in the ranking is connected to the headquarters of their companies, shown on the map with live stock prices, and to their private jet when it is in flight.
That connection makes the abstract figure tangible: you can see where the companies sustaining a fortune are physically located, how they are trading at this moment, and (if their owner is crossing the sky) the route they are flying. We explain the corporate layer in detail in corporate headquarters on the map, and the aerial tracking in how celebrity private jets are tracked. If you are interested in the floating half of these fortunes, we have also explained how superyachts are identified.
Frequently asked questions
How does Forbes know how much money someone has?
It does not know, it estimates, using a documented method. For stakes in publicly traded companies, it uses public regulatory filings and market prices: this is the solid part of the calculation. For private companies, real estate, art, and collections, it applies valuation by comparables and conservative appraisals. It then subtracts what liabilities it can document. The result is a reasoned estimate reviewed by a research team, not an audit of anyone's personal accounts.
Why does net worth change every day?
Because most of these fortunes consist of shares, and shares trade. When a billionaire's primary company rises or falls on the stock market, the value of their stake (and therefore their estimated net worth) moves in the same session. That is why real-time rankings exist: the annual snapshot becomes outdated within hours when the underlying asset is so volatile. A headline about billions «lost» in a day almost always describes a share price drop, not money spent.
Are wealth rankings accurate?
No, and the publications themselves acknowledge this. The portion linked to publicly listed shares is fairly precise; the rest accumulates uncertainty: private companies valued by comparables, debt and pledged shares that do not always surface, family wealth distributed across vehicles that are hard to attribute. The fact that Forbes and Bloomberg publish different figures for the same individual is the best evidence that these are estimates with their own criteria, not measurements. The useful reading is the trend and the order of magnitude, not the decimal place.
Is net worth the same as cash in the bank?
No. Net worth is primarily value: what the market says corporate stakes, real estate, and collections are worth. Immediately available cash is usually a small fraction of that total. To obtain liquidity without selling (and without paying the taxes and market signal costs that selling implies) many large fortunes rely on margin loans secured by their shares. This is why someone can top a global wealth ranking while financing their purchases with debt.
Conclusion
Billionaire net worth is an estimate with a method, not a balance: solid where there is a stock exchange, approximate where there are appraisals, and blind where there is opacity. Read with that awareness, the ranking becomes an excellent tool for understanding who accumulates what and how it evolves. And read on a map, even more so: open the map and explore the Forbes-updated wealth ranking, connected live to the companies those fortunes depend on and the jets that carry their owners across the sky.
Frequently asked questions
How does Forbes know how much money someone has?
It does not know, it estimates. The methodology sums the market value of stakes in publicly traded companies, values private companies using comparable transactions, adds real estate and other assets with conservative discounts, and subtracts known liabilities. It is a documented estimate, not an audit.
Why does net worth change every day?
Because most of these fortunes are shares, and shares trade. When a billionaire's main company rises or falls on the stock market, their estimated net worth moves with it in the same session. That is why real-time rankings exist.
Are wealth rankings accurate?
No, and their own authors acknowledge it. They are reasoned estimates with a margin of error: privately held companies, art collections, private debt, and family fortunes split across many vehicles are all hard to value from the outside. The trend is more reliable than any precise figure.
Is net worth the same as cash in the bank?
No. Net worth is primarily the value of corporate stakes and other assets, not immediately available cash. A billionaire on paper may have relatively little liquidity without selling shares or borrowing against them.